
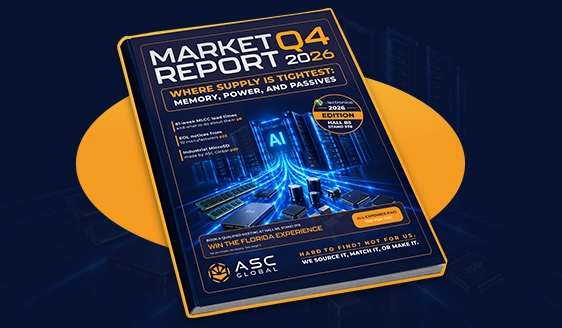
Receive Your Market Report
Get the latest PDF version of the report, all future reports, occasional surveys, and special offers delivered right to your inbox.
For information on our commitment to protecting your privacy, please review our Privacy Policy.
Lead TImes
EOL Reports
News Flash
Testing Analysis
Earning Recap
Products & MFRS
LEAD TIMES
We cover the current lead times and pricing trends for Analog, Power, Passive, Memory, Logic & Digital, and Electromechanical components.
The Numbers Behind the Demand
We cover the current lead times and pricing trends for Analog, Power, Passive, Memory, Logic & Digital, and Electromechanical components.
| Stat | Label |
|---|---|
| 61 weeks | Factory lead time listed for some Samsung Electro-Mechanics MLCCs, October 2026 |
| 10x | MLCCs in an AI server compared with a conventional server |
| +23% | Price rise on a 47 µF high-capacitance MLCC, August to October 2026 |
| +10 to 15% | Q4 2026 conventional DRAM contract price forecast |
| +15 to 20% | Q4 2026 NAND flash contract price forecast |
| 6 months | Lead times on part of the Analog Devices portfolio, per its July notice |
Sources: TrendForce, distributor listings, and Analog Devices customer notices, as reported in October 2026.
END-OF-LIFE REPORTS
We highlight the EOL components from major brands, helping companies manage obsolescence and plan for replacements.
Industrial MicroSD &
Semiconductor Supply Chain Updates
Explore our latest articles covering industrial-grade MicroSD solutions, the Diodes Inc. component shortage, and the impact of Section 232 semiconductor tariffs on global procurement and supply chain resilience.

WHERE SUPPLY IS TIGHTEST:
MEMORY, POWER, AND PASSIVES
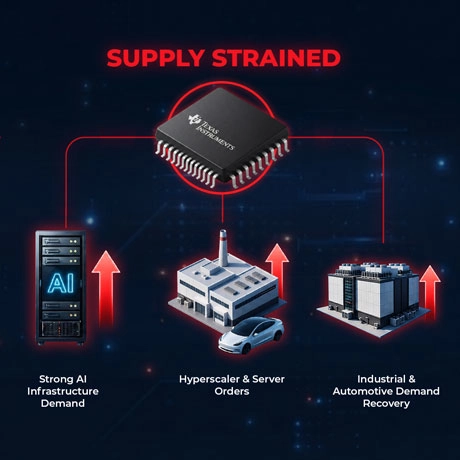
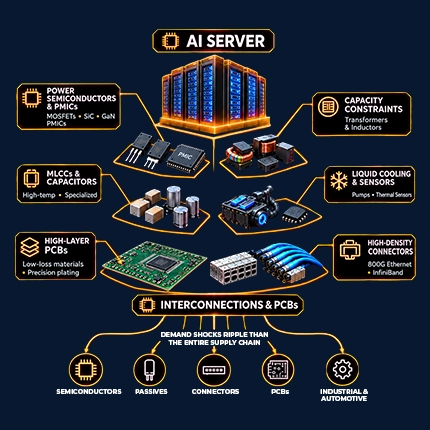
AI infrastructure demand is tightening the availability of critical electronic components, creating supply challenges that extend beyond data centers into industrial and embedded applications. ASC Global examines the impact on memory, power management, and passive components, highlighting key risks and sourcing strategies manufacturers can use to protect production continuity.
- Critical Component Constraints: DDR5, enterprise SSD/NAND, PMICs, power MOSFETs, and advanced capacitors face increasing demand, with reported lead times reaching 40+ weeks for some memory configurations and 20+ weeks for specialized MLCCs.
- AI-Driven Supply Pressure: A single NVIDIA GB300-based AI server can require approximately 30,000 MLCCs, intensifying competition for essential components.
- Proactive Sourcing Strategies: Verify allocations early, establish risk-based safety stock, qualify alternative components, and review future BOM requirements to minimize shortage exposure.
DDR3 and DDR4: Planning for the Memory Exit
DDR3 and DDR4 remain critical to industrial equipment, factory automation, networking, medical devices, and embedded systems. As manufacturers shift production toward newer memory technologies, securing authentic legacy components requires proactive obsolescence planning, demand forecasting, and qualified sourcing strategies to protect long-term production and service requirements.
- EOL and Obsolescence Planning: Identify product discontinuation risks, evaluate last-time-buy (LTB) windows, and forecast memory requirements based on production volumes, maintenance needs, and equipment support lifecycles.
- Strategic Last-Time Buys: Calculate purchasing quantities using projected demand, existing inventory, repair requirements, and contingency allowances to prevent shortages without creating excessive inventory.
- Qualified Component Alternatives: Evaluate replacement options, including pin-compatible devices and newer memory configurations, while verifying electrical specifications, timing, firmware compatibility, and system-level requirements.
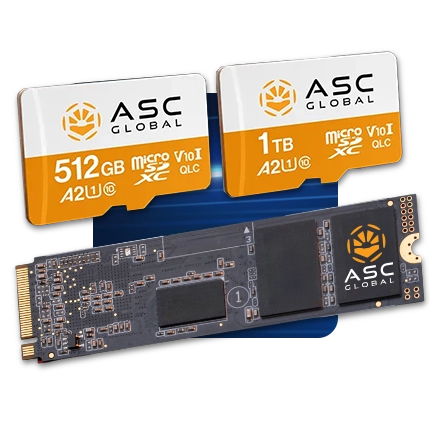
Made by ASC:
Industrial MicroSD and Custom SSDs
When a qualified storage part is discontinued or allocated, ASC Global builds a drop-in replacement to your specification, with a locked bill of materials and scheduled supply.
-
Industrial MicroSD: 512MB to 1TB, SLC, pSLC, MLC, and TLC options, -40°C to +85°C industrial configurations, up to 1.5 million units a month, and a first order in about three weeks.
-
Custom SSDs: 64GB to 30TB in 2.5" SATA, M.2 SATA, M.2 NVMe, and enterprise NVMe (U.2, U.3, E1.S), with up to 6,800 MB/s sequential read.
-
Supply program: free engineering samples, fixed-BOM lifecycle with PCN and EOL notice, scheduled supply, and full traceability.

Strategic Recommendations
for Procurement Leaders
From industrial-grade memory solutions to component shortages and evolving trade policies, timely market intelligence is essential for minimizing risk and maintaining production continuity. Explore our latest insights to make more informed procurement decisions and strengthen your supply chain strategy.
PRICE ACTION TRACKER
Since February, nine suppliers have issued 16 dated price rounds across analog, power, passives, and MCUs. A spring quote has usually been superseded. A sample of this year's rounds:
| Effective | Manufacturer | Scope | Reported Change |
|---|---|---|---|
| Sep 28 | NXP | Selected products | About 10%, varies by part |
| Jul 1 | Infineon | AI-server power, automotive power discretes | 10 to 20% |
| Jul 1 | Yageo | Entire capacitor portfolio, including MLCCs | Broadest increase in years |
| Feb 1 | Analog Devices | Portfolio-wide, including backlog shipping after the date | About 15% average, up to 30% military and high-rel |
How increases compound
A part at $100.00 rises to $115.00 after a 15% round, then to $126.50 after a further 10% round. Two rounds add 26.5%, not 25%, because the second applies to the already-raised price.
Allocation Watch
Supply alerts by category, gathered from distributor and customer reports this quarter. These are channel-reported and not confirmed by manufacturers, so verify part by part before acting.
FPGAs
Lead times for some FPGA families are reported near 60 weeks, with forecasts requested through 2028. Some industrial programs report waits beyond 18 months on older device families.
Legacy DDR3 and DDR4
DDR3 book pricing is reported up about 50%, with DDR4 up about 10%. At least one networking account was reportedly told to expect no industrial DDR4 allocation, prompting large pre-buys.
Six more categories in the full report: DRAM and RDIMM, analog, passives, power and discretes, continuity risks, and data center hardware.
TEST & FAILURE RATES
In Q3 2026, diodes and transistors showed the highest failure rates, indicating stress in power and signal paths. MOSFETs followed, while FPGAs and logic ICs required ongoing validation. Memory, MCUs, RF, and power management devices recorded lower but persistent test exposure across industrial and communications systems.
By Device Type
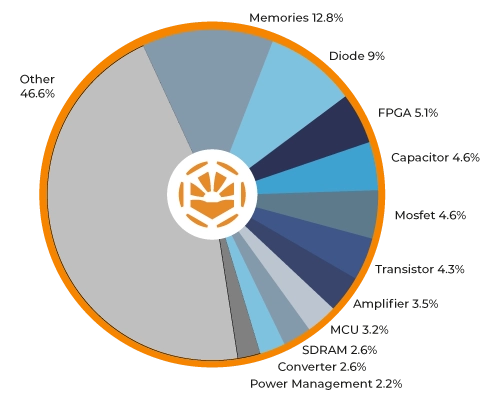
Top 10 Component Types by Failure Rate
| 1. Microprocessor 2. Inductor, Coils, Chokes 3. Module 4. Transformer 5. Suppressor |
6. Audio 7. Voltage Regulator 8. Modulator 9. System on a Chip (SoC) 10. DRAM |
This ranking is determined by the proportion of failed results compared to the total units tested in each category. While some failures stem from aging or mishandling, others could indicate more serious quality issues or potential counterfeit threats
Hot Commodities
Part numbers our buyers are watching this quarter. Four of the 12 on our list:
| Part Number | Manufacturer | Lead Time (weeks) |
|---|---|---|
| ADA4807-2ARMZ | Analog Devices | 43-54 |
| MT41K256M16TW107P | Micron | 40-53 |
| ICM42688P | TDK | 45 |
| KSZ8999I | Microchip | 26-40 |
EARNINGS RECAP
This report summarizes the latest earnings results from the biggest brands in electronic components, highlighting key trends and financial insights.
AUTOMOTIVE
Toyota Motor Corp.
- Revenue: $84.50B (+10.4% YoY)
- Net income: $9.20B
- Net Profit Margin: 10.9%
General Motors
- Revenue: $48.03B (+1.9% YoY)
- Net income: $1.31B
- Net Profit Margin: 2.7%
Ford Motor Company
- Revenue: $48.30B (-3.8% YoY)
- Net income: -$1.33B
- Net Profit Margin: -2.7%
PRODUCT UPDATES
MANUFACTURER UPDATES
For more news and industry insights dive into our Component Compass
Q4 2026 Market Report
Why are MLCC lead times so long in Q4 2026?
The ASC Market Report is a quarterly analysis of the electronic components and semiconductor market, written for procurement teams, supply chain managers, and engineers making component sourcing and planning decisions. Each edition covers the supply and demand dynamics, pricing trends, lead time forecasts, and inventory conditions shaping the market for the coming quarter.
The report draws on ASC's global sourcing network and market visibility across nine office locations to produce analysis that reflects current conditions across regional markets and distribution channels. Topics covered in recent editions include the AI-driven memory supercycle and its effects on DRAM and NAND Flash availability, supply chain realignment driven by tariff and geopolitical developments, industrial MicroSD manufacturing constraints, and the Diodes Inc. shortage affecting procurement teams across multiple end markets. The aim of each edition is not to summarize news that has already been widely reported, but to interpret market conditions in terms of what they mean for sourcing decisions in the quarter ahead.
How much are DRAM and NAND contract prices expected to rise in Q4 2026?
TrendForce expects conventional DRAM contract prices to rise another 10 to 15% in Q4 2026 and NAND flash 15 to 20%, after record increases earlier in the year. Memory makers are moving capacity to HBM, server DDR5, and enterprise SSDs, which leaves DDR4, eMMC, and commodity NAND with tighter supply. The Q4 Market Report shows lead times and open-market availability for NAND, NOR, DRAM, memory modules, eMMC, and SSDs.
How do I calculate a last-time buy for DDR3 or DDR4 memory?
Multiply annual production by the remaining support years and the modules per system, then add an allowance for repairs and scrap. For example, 1,200 systems a year × 5 years × 1 module × a 15% allowance = 6,900 modules. Adjust for existing stock, committed supply, minimum order quantities, and planned redesigns. Before you commit, confirm how long the equipment stays in service and whether qualified alternatives exist. The full report walks through the calculation and the engineering checks for replacements.
Which electronic components were announced end-of-life this quarter?
The Q4 2026 Market Report tracks 20 end-of-life notices from 10 manufacturers, including Texas Instruments, Analog Devices, STMicroelectronics, Infineon, NXP, onsemi, Microchip, Renesas, Vishay, and Diodes Inc. EOL dates run from October 2026 to December 2028. Some parts have pin-to-pin replacements, some change package, and at least one, the STMicroelectronics TESEO-LIV3F GNSS module, has no replacement listed. The full report includes the replacement path for every part.
How do we access the Market Report, and is there a cost?
The Market Report is free. Register with your name, company, and email on this page to receive the Q4 2026 PDF and every future edition. You don't need to be an ASC Global customer. The report is written for procurement teams, engineers, and supply chain professionals who need current lead times, pricing trends, and EOL notices to plan their sourcing.