

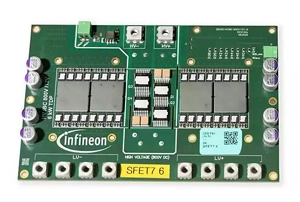
Infineon and NVIDIA Advance GaN Power Solutions for AI Data Centers
Infineon and NVIDIA are expanding their collaboration to develop gallium nitride (GaN)-based power converters for 800V DC AI data centers. Designed for NVIDIA’s MGX architecture, these solutions aim to improve efficiency, increase power density, reduce cooling requirements, and support racks consuming up to 1 MW. Deployment is expected to begin gradually in 2027.
Tesla and NVIDIA Invest in Samsung’s Advanced AI Chip Substrates
Tesla and NVIDIA are reportedly committing KRW 3.7 trillion combined to expand Samsung Electro-Mechanics’ advanced FC-BGA substrate production in South Korea. Tesla’s KRW 1.1 trillion investment secures supply for AI chips used in autonomous vehicles and Optimus robots from 2029–2033. NVIDIA’s reported KRW 2.6 trillion commitment supports expanded capacity for AI data center semiconductors, addressing growing substrate supply constraints.
Samsung Upgrades Xi’an Plant to 286-Layer NAND for AI Storage Demand
Samsung is reportedly upgrading its Xi’an, China, facility from approximately 200-layer NAND to 286-layer V9 technology to meet growing AI data center storage demand. The plant accounts for roughly 40% of Samsung’s global NAND output. Monthly production targets reach 5,000 wafers by December 2026 and 40,000 by December 2027, subject to U.S. equipment licensing requirements.
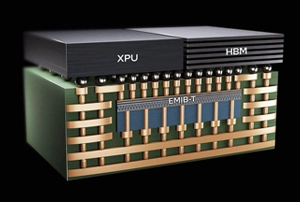
Google Retains Intel EMIB-T Despite Low Yields and Potential Delays
Google is reportedly sticking with Intel’s EMIB-T advanced packaging for its HumuFish TPU v9 despite substrate yields of around 35% in Q3 2026, below the 50% year-end target. Intel and suppliers are working to improve yields. Design revisions could delay tape-out until January 2027 and shipments to Q1 2028, testing Intel’s ability to secure major AI-chip packaging customers.
Infineon and Wolfspeed Expand SiC Wafer Supply for Power Semiconductors
Infineon and Wolfspeed have extended their long-term silicon carbide (SiC) wafer supply agreement to include 200 mm substrates alongside existing 150 mm wafers. The multi-year deal supports Infineon’s transition to larger-wafer manufacturing, improving potential production efficiency and supply-chain resilience. SiC demand is growing across electric vehicle charging, renewable energy, energy storage, and AI data center power infrastructure.
Global Smartphone Shipments Plunge as Memory Costs Surge
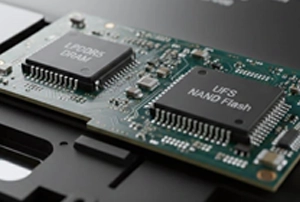
Global smartphone shipments fell 22% year over year to 255.3 million units in Q3 2026, marking the steepest quarterly decline recorded by IDC. Soaring DRAM and NAND prices, driven by AI infrastructure demand, increased manufacturing costs and pressured consumer affordability. Samsung and Apple gained market share, while Chinese brands faced sharper declines.
Get biweekly updates to your inbox
More Component Compass news
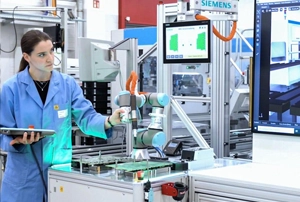
Siemens and NVIDIA Deploy Industrial AI to Accelerate Manufacturing
Siemens and NVIDIA are deploying AI-powered digital twins, synthetic training data, and AI agents at Siemens’ Erlangen factory in Germany. The technologies could reduce PCB inspection engineering effort by up to 85% and time-to-market by 40%. AI-driven production planning could also deliver cost savings of up to 20%, helping manufacturers respond faster to changing orders and material shortages.
LX Semicon Exits SiC Market Amid Slowing Electric Vehicle Demand
South Korea’s LX Semicon is selling more than 60 silicon carbide (SiC) patents covering power semiconductor devices and epitaxial wafers, formally exiting the market. Valued at less than KRW 1 billion, the sale reflects slowing electric vehicle demand and financial pressures. The company plans to refocus resources on core businesses, particularly display driver ICs.
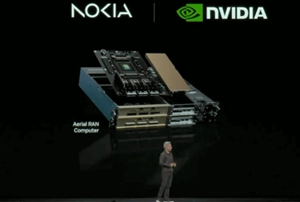
Nokia and NVIDIA Advance AI-RAN Toward Commercial Deployment
Nokia and NVIDIA are advancing AI-powered radio access networks (AI-RAN) to improve 5G performance and support future 6G and physical AI applications. Trials with BT, Deutsche Telekom, Elisa, and Orange are testing AI-driven signal processing, network capacity, and edge intelligence. Deutsche Telekom reported initial laboratory uplink throughput improvements of 10–15%, with broader commercial deployments expected to progress in 2027.
U.S. Government Takes Stake in Helion to Advance Fusion Semiconductors
The U.S. government has agreed to provide Helion with up to $175 million under the CHIPS Act in exchange for a non-voting equity stake. The funding will support high-voltage semiconductor research, advanced packaging, and power-module manufacturing. An additional $50 million in private investment will help strengthen domestic capabilities for fusion energy systems and future power infrastructure.
TDK Launches Compact Y1 Capacitors for High-Temperature Power Applications
TDK has introduced its B3201 series of compact Y1 safety film capacitors for automotive and industrial power electronics. Rated for 500 V AC and up to 1,500 V DC, they operate at temperatures up to +125°C with derating. Capacitance ranges from 0.47 to 33 nF, supporting EMI suppression in EV chargers, industrial drives, renewable energy systems, and power supplies.
Qualcomm Plans Global Job Cuts Amid Smartphone Market Slowdown
Qualcomm plans worldwide workforce reductions following annual performance reviews, with employee notifications expected to begin in November 2026. CEO Cristiano Amon cited performance and evolving business needs, but the company has not disclosed the number of positions affected. Weak smartphone demand and rising memory prices add pressure as Qualcomm expands into AI data centers and diversifies beyond handset chip sales.
Component Compass Timeline
Infineon Nvidia Gan Power Solutions AI Data Centers
Qualcomm Chip Price Increases Supply Pressures
GlobalWafers Semiconductor Wafer Supply Imbalance
STMicroelectronics MCU Price Hikes, Apple Device Inflation, and Micron–Anthropic AI Memory Supply Shift
SK hynix and NVIDIA Forge AI Memory Alliance
United States Quantum Package Directs Billions
Major Chip Suppliers Implement Aggressive April Price Hikes
Texas Instruments and Infineon Raise Chip Prices Amid AI Demand
Siemens Energy Invests $1B to Expand U.S. Manufacturing
Nexperia Conflict Deepens Threatening Chip Stability
Market Report
For more news and industry insights dive into our Market Report
INDUSTRY UPDATES
ASC Global brings you with our Component Compass report the latest semiconductor industry findings to provide valuable guidance for maneuvering market intervals. We excel in supply chain strategies that effectively address market volatility.
If any questions or concerns arise, kindly reach out to your Account Manager or our support team at info@ascglobal.com | +1 954 718 2950.